Showing posts with label person::nassim taleb. Show all posts

Friday, December 23, 2011

Sissyness Vs Courage

There's a minor difference but an important difference. Both personalities are obsessed with Randomness, the only difference being, that sissies are afraid of randomness and someone with courage looks at randomness in the eye. Leaving political innuendos aside, it reminds me of the hanging of Saddam Hussein, who looked at fate in the eye and did not blink when he was hanged. What could be worse than to look at people abusing you when you are about to die, but he did not blink. There is something terribly attractive about such a death, it has the power to wash away your past sins and make you immortal.

Bhutto was another one of these anti-sissy souls. Who met his fate with courage and a sense of bravado. The man had committed many sins, but his death immortalized him. Three generations down the line, people still chant slogans like "zinda hae bhutto zinda hae" (translation: Bhutto still lives, Bhutto still lives).

Never live like a sissy and never be two faced. Their should be no contradiction between your private and your public life. You have the right to hide your private affairs and your private opinions, but you have no right to contradict your private affairs and opinions in you public life. That requires courage. 

Now some ideas on leadership. Business schools are obsessed with imparting skills to leaders, honing their presentation and personalities, failing to realize that leadership has nothing to with the outward or the apparent. It has everything to do with belief.

"A leader is someone who does not come up with a new idea, but he is the first one to believe in that idea, and whose belief is so strong and so blind, that he is the first one to suffer because of his belief"

Saturday, June 11, 2011

Nassim Taleb on Finance

Wednesday, May 25, 2011

Black Swan of Cairo

How the idea of having "GOALS" in life is completely MISGUIDING

Pick up any of the popular self-help books, or search any motivational website and you'll come across literature incessantly proselytizing "GOAL Setting". The key to success is all about having the right goals and pursuing those goals doggedly.

"Obstacles are what you see when you take your eyes of the goal"

Now this quote is from Vince Lombardi who was a football coach. Football is taleb's proverbial extremistan where the superstar effect takes hold.  Now, this quote makes a lot of sense to someone who got successful in a field dominated by luck, but a much better version of the quote would read like this:

"Opportunities are what you see when you take your eyes of the goal"

Even Vince Lombardi was a failure at many things he did, above all as a father. He failed at many different things during his lifetime and only probably settled at something which he thought he could be good at. Quitting at the right time was probably the key to his successes. He quit law school probably because he couldn't see himself as a lawyer, although according to him he needed to settle down and start a family. Success would in this context mean that one needs to at times settle down and just focus at the task at hand. You look for passion/pleasure at work only when you don't have a personal life. Marriage probably solves a lot of these problems by providing a good substitute. With a marriage and responsibility you wouldn't be spending time day dreaming and looking for distant opportunities.

The assumption behind setting goals is you know everything about everything. These goals are set apriori, which basically means that they are based on some sort of projection or extrapolation of the present environment. You cannot set a long term goal without making massive assumptions about what the future is going to look like and what your place in that future will be.

As I have learned from experience, the future doesn't look anything like you've imagined. And setting goals, at least long term goals is a very foolish proposition. Anyone who continues to pursue a long term goal even when the future he had in mind, changes, is a fool himself. The key to success it seems is not to pursue goals altogether, but to live in the present and to learn to quit as soon as possible. Quitting it seems is far more effective than any strategy for success. Opportunities open up all the time around you, and we must open our eyes for these opportunities.

Life is in essence subtractive. You need to figure out what not to do, than to find out what to do and pursue it doggedly. Look around you and grab opportunities when they appear, because they are very rare.

Thursday, April 14, 2011

Calvin Newport and Wrong Advice

Before starting, I would make one thing clear that I really admire Calvin Newport's writing and it provides great insight about how work should be done. After all, MIT epitomizes brutal work ethics and to manage that and still have a life is something truly remarkable. This insight provides people like me with the opportunity to somewhat decode what remarkable people do to get to where they are.

But there is one problem, it's good to have a remarkable work ethic  but it would do you no good if that work is not valued. You can be a superstar at digging ditches or flipping burgers but it will not get you very far and that will make you lose your work ethic.

Just to illustrate one horror story, the person has a remarkable work ethic but the work metaphorically requires digging ditches. Sadly, he hasn't gotten far and is now angry, miserable and without money.
http://phdtips.blogspot.com/

Downplaying passion is always important, but sometimes downplay hard work should also be considered.  Everyone loses passion about his work if he is made to do that work day in and day out with very few breaks in between. Similarly, you will lose your work ethic if you know that there is nothing at the end of the tunnel.

One of my favorite Nassim Taleb quote is that:
"Preoccupation with efficacy is the main obstacle to a noble, poetic, elegant, robust and heroic life"


When I read Cal's blog, I feel that Cal is preoccupied with "efficacy". The nature of his work forces him to be preoccupied with it. Most of his posts stress on being a superstar and he clearly defines a simple method to being one (which works by the way). But the problem is that if everyone becomes a superstar then you'll only end up raising the bar for being a superstar. A positive feedback loop would be formed. Everyone reading Cal's posts would suddenly do better but the standard of better would change and we would then have to come up with something....."better". This reminds me of George Soros' reflexivity theory.


WIKIPEDIA:
Reflexivity refers to circular relationships between cause and effect. A reflexive relationship is bidirectional; with both the cause and the effect affecting one another in a situation that does not render both functions causes and effects. In sociology, reflexivity therefore comes to mean an act of self-reference where examination or action 'bends back on', refers to, and affects the entity instigating the action or examination. In this sense it usually refers to the capacity of an individual agent to recognize forces of socialization and alter his or her place in the social structure.

So the problem is in a way compounded. Improving your work ethic would simply make you improve it more in the future. As I look around, I see that the most successful people are those that aren't very brilliant and have a relatively poor "work" ethic as defined by Cal Newport. In Academia, where everything is structured and to an extent properly defined, this might work (I suspect it doesn't).

Do we work for passion or for money or to be superstars? The question itself is hard to answer but there is a certain ambiguous and unclear criterion of success in every field which would be hard to put in words. Success is also relatively defined. You can just look at a person and judge him to be successful or not in an ambiguous and split second intuition. Somebody who is extremely happy with his work and professional life but hasn't been an outstanding employee is inspirational and motivating at times. On the other hand, somebody who has assumed leadership roles but seems to be depressed and overworked might be considered a sorry sight.

As I look around myself, people work for different things, but superstars are never defined by their work ethic. The number one reason for being a superstar is networking, and not just normal networking. It is the type of networking that would make people trust you blindly, say bad things about you but they would still be willing to give you a chance. Making friends and keeping them is a talent that comes naturally. You could improve on it, but the talent comes from within. Somebody who is autistically inclined would love to read books but wouldn't be much interested in people.

In the research field even, networking plays a much more important role than whatever work ethic you possess. Success is not a mathematical equation where it is proportional to the number of papers you have published. Scalability of those papers is important. You can work alone and at best publish 1 paper a year, or you can be scalable and publish 5 papers in a group.

Scalability is everything, networking gives you the opportunity to become scalable. No one would in the end really look into you and see if you possess a good work ethic. I know of people who have possessed really poor work habits but have used their charm to get work out of people who weren't even their subordinates. The ability to get names into papers, where one has done nothing, is true ability and by passes work ethic. It is called being tactful and charming. Steve Wozniak and Steve Jobs are good examples of this. One has charm and the other has grit. When building a narrative people will write about how hardworking Steve Jobs really is, but that is how we want to see him, when in reality he might just be in it for partying and as a side venture would be selling his apple story. A true superstar is one who understands humans and knows how to take advantage and make things scalable. As I read numerous autobiographies of Edison, I realized that although the person had a remarkable work habit, but it never was his work habit that distinguished him. Almost everyone has a remarkable work habit. Even people who are complete failures have remarkable work habits. The real talent is to make things scalable and to understand humans and human nature.

Another of Taleb's quotes:
"A loser generally bemoans mankinds flaws, contradictions, irrationality; without exploiting them for fun and profit."


Success is a side effect of scalability. Even failures work hard or may have superior work ethics. If passion has to be downplayed then so does work ethic. Passion and work ethic are no match if somebody has the charm and ability to manipulate and control and take advantage of other people's emotional flaws.

So next time if you hear about Edison or Steve Job or Bill Gates, then don't think that they work hard and therefore they are successful, because failures work hard as well. What truly distinguishes success and failure is the ability to make things scalable, the ability to network and charm and control other people.

Scalability and Career Options


One important distinction is still pending and that is that you cannot possibly make non-scalable career or profession scalable. If you're a doctor, then there is only a limited number of patients that you would handle. Your income growth would never be nonlinear, which might be the case if you are in finance.

Never chose a career which is dominated by super stars. Any field that has superstars is dominated by power law distribution where a few superstars get all the acclaim (and the money) while the rest are all considered losers who struggle hard to attain this elite category. Academics is one such field where one superstar ends up with everything while the rest will always be treated as losers. Plus, everyone in academia has more or less a remarkable work ethic, but it is very difficult to remove your loser tag and replace or topple a superstar. So a select few would end up with tenure, while the rest will slave the rest of their life for part time academic jobs.

Gaussian deterministic careers like Medical Doctors have no superstar phenomenon. The credit is always equally distributed (in a guassian way) with few fat tails. I was also reading stats on petroleum geologist who are paid well with few fat tails. Everything is well distributed around a mean.

Hence, if you are starting a profession then carefully read the following;

  1. Choose careers which is not dominated by superstars. Academic careers are dominated by superstars. If you can't find a person in the field who inspires you about that field, then that field has no superstars and might be the right choice for you. Telecom engineers, geologist etc (not writing, academics etc).
  2. Work ethic and passion are not that important. Improving your work ethic wouldn't get you far because even failures have excellent work ethic. Focus on the human side and try to manipulate and take advantage of people's biases.
  3. If you're treated like a loser in your field, then you'll lose the ability to be passionate and hard working. Try not to chose careers with superstars who would make you look like a loser.

Watch this video at the end, where a life of a has been wannabe WWE wrestler is described. Never be a part of a profession with superstars and dominated by power law distribution. Your life would be miserable. That includes Academia as well.


Wednesday, April 13, 2011

Suppressing risk only increases tail risk and chances of blowups

All natural things are Gaussian in nature.

Take wealth distribution for example. The moment a person becomes increasingly wealthy, then his chances of being robbed or blackmailed increases. In more traditional countries, people go out of their way to act poor so that the risk of getting robbed or blackmailed is reduced. This keeps the distribution more or less Gaussian.

But the problem becomes nonlinear once someone introduces laws that protect property and ensure safety. The moment such laws are introduced to protect a person's wealth then his wealth grows nonlinearly and exponentially. The end result is that if you sample 100 people, then 90% of the wealth would be distributed among 1-5 persons while the rest would be classified as poor. Without law and regulation, the 95 poor souls would try and rob these 5 rich people. So laws and regulations make the rich more infrequent but their impact is greater.


The clip above is a must watch. The clip is about traffic in the absence of any regulation. The traffic apparently flows very smoothly with little or no hindrances. Now some people would criticize the absence of law on the roads in Iran. But the traffic accidents are Gaussian in such a situation. People will drive slowly and carefully and there will be more accidents but of less severity. Now, suppose this is a developed country with first world road rules. Then, their would be lesser traffic accidents but the drivers would drive faster and less carefully and when a traffic accident happens then it would be more severe.

So, is law making distributions prone to tail risk.

PS: I have driven in the roads shown in the video and trust me, I feel a lot safer, drive a lot slowly and carefully compared to driving on a motorway in a developed world.

Tuesday, February 22, 2011

New Chapter on Heuristics

Thursday, February 10, 2011

Critique of Taleb


http://www.efalken.com/papers/Taleb2.html


This guy wrote a piece criticizing Taleb and his simple strategy for avoiding risk. The concept of a blowup, models and predicting the future is alien to the writer. Major discoveries, stock movements etc are all unpredictable. 

Taleb once showed a graph (10 year) of S&P 500 with 10 days taken out. After removing those 10 days, the S&P lost 50% of its worth. Anyways, I am attaching the critique which is basically written out of desperation by an autistic savant who seems to be entirely future blind.


Nassim Taleb's Black Swan

Nassim Taleb is a former trader who wrote a textbook on option and market making, and then became more philosophical in his best seller Fooled by Randomness, and now in The Black Swan.  His big idea is that sometimes, unexpecting things happen: countries dissolve into anarchy, wars start, unknown authors become famous. His secondary ideas are variations on this theme, that people, especially experts, are generally biased, overconfident, and rationalize past event so they appear deterministic. Stated baldly, these assertion are hardly novel but true enough, and one can argue about their relevance in various cases. As a highly popular presentation of ideas near to my interests and vocation, I think it is worth critically examining if there is anything to his particular contribution to the literature on cognitive biases or social failures. My conclusion, in short, is no.
Taleb’s style is to severely criticize experts and authorities--lots of 'moron', 'idiots', and 'fools' out there--while implying that both he and his reader or listener are exempt from their many biases.  Reading someone deflating puffed-up egos, criticizing the insular world of academics, and suggesting the experts have a huge blind spot on something important, can be fun reading.  But it has to be making points that are true if new, or important if true, and here he fails to deliver.
For someone advocating doubt and criticizing expert and 'regular' people’s overconfidence and arrogance, Taleb’s writings are filled with certainty, anger, and immodesty, having the Godelian impossibility of someone shouting 'I am the most humble!'  Indeed, his current popularity based on prescience in forecasting recent events, and his emphasis that this proves him correct is exactly the kind of naive comfirmation based on small samples that he argues is sloppy thinking. Consistency is not a hobgoblin in Taleb's mind.
While people are generally overconfident about their diving ability or common sense, does that same overconfidence lead people to underestimate the probability of market crashes, and thus the price of insurance (eg, put options?)   The data suggest the opposite is true, that is, that people overpay for such improbabilities based on hope.  Survey data on beliefs are not necessarily economically important, because markets elicit results not from unmotivated an ignorant masses, but from a highly motivated and informed subset.  People willing to offer ‘a side’ to such a bet tend not to be biased, and also pad their bets with a considerable safety margin so that their errors are not catastrophic, which in practice means you obtain much lower odds for improbable events than what simple surveys would imply.
A major theme of Taleb is that models of uncertainty are too precise, and this thread has a long history. Taleb's sometime co-author Benoit Mandelbrot has been trying to sell the world on the big idea of fractals in finance for several decades.  James Gleick’s Chaos outlined the essence of Benoit Mandelbrot’s fractals, which takes a simple few lines of inputs to create graphics of insane complexity yet also beautiful recursive symmetry, in many cases eerily similar to nature (eg, ferns, snowflakes).  In dynamic systems, you have chaotic systems that are purely deterministic though sufficiently complex that they appear random.  These systems have large jumps, or phase shifts, reminiscent of market crashes or sudden bankruptcies; they have butterfly effects where small changes produce big differences in outcomes.  Mandelbrot and others have been trying to apply these ideas to financial markets for many decades now (since 1962!), and the effort has not gained any traction, in spite of many papers applying this concept (search skew or kurtosis in any financial journal and you will see many papers).  Mandelbrot’s big idea in finance is that finance relies on a profoundly flawed assumption, mainly that market prices are normally distributed. Mandelbrot argues market prices have much fatter distributions described by Cauchy distributions, as evidenced by the high number of 5+ standard deviation moves in financial markets.

The result of these mistaken assumptions is to understate risk, according to Mandelbrot, and so overprice stocks and underprice options, and also understate the capital cushion financial institutions need to withstand market risk.   Mandelbrot’s alternative approach is based on new parameters that would replace the mean and standard deviation.  His first parameter is Alpha, derived from Pareto's Law, is an exponent that measures how wildly prices vary. It defines how fat the tails of the price change curve are. The second one, the H Coefficient, is an exponent that measures the dependence of price changes upon past changes. Unfortunately, Mandelbrot himself acknowledges in The Misbehavior of Markets that no two individuals calculate the same Alpha and H Coefficient when using the exact same historical data: there is no unique way to calculate these two parameters. Thus, using one method, you could derive Alpha and H coefficients that suggest a stock is risky, using another method you would reach the opposite conclusion. This flaw probably has some bearing on its lack of practitioner popularity.
Frank Knight, meanwhile, in his classic Risk, Uncertainty, and Profit in 1921, outlined the basic idea that it is uncertainty, in the form of non-quantifiable dispersion, that is at the root of profits. The basic idea is that risk, once quantified, is diversifiable, and thus becomes risk-free.  If you know that your champagne bottle could burst while fermenting with probability p, that number becomes very manageable the larger your operation via the law of large numbers.  Economists have been intrigued by this notion ever since, but by definition it is unquantifiable so when you write down a random process, it is no longer Knight-like, making it rather elusive.  However, when we come up with uncertainty proxies, such as volatility (surely more volatile assets are generally more uncertain), leptokurtosis (asymmetric tails), or analyst or investor disagreement, the results do not have any obvious empirical implication beyond the fact that they exist. That is, assets with greater downside tail, or analyst disagreement, conditional upon gaussian volatility measures, are not predictive of future returns.
Taleb’s career as a talking head started in 1996 when, as the author of a niche derivatives text, his claim in Derivatives Strategy magazine that the new Value-at-Risk phenomenon was worse than useless made for great debate in risk management circles.   I was leading a Value-at-Risk project at the time, so of course I found his criticisms of interest. JPMorgan had just introduced this method of aggregating risks in a highly popular practitioner brief.  Their approach, RiskMetrics, outlined in detail the methods of estimating volatility when you had a portfolio of currencies, bonds, equities, and even options.  Previously, financial books that contained bonds, currencies, equities, etc., each had little silos of risk reports, but this showed how they could be combined, basically by putting everything into a factor approach, in which every asset has a sensitivity to a factor, and every factor has a certain correlation and volatility.  This was not new—factor analysis had been around for a while—but its clear application to a tangible problem was insightful, and created a lot of buzz.
Value-at-Risk was not a panacea, but it was an improvement (the only people who use the word 'panacea' are critics).  Taleb’s criticisms of VAR then are similar to his criticisms now: that a metric is not flawless, and those who believe parametric applications of VAR are fools. In a trivial sense he is right, but in the case of VAR, or specific parametric statistics, or expectations in general, there are many users who understand that tools need to be supplemented by judgment, adjustments for the parochial realities of various asset classes with their various deviations from pure 'normality'.  It is a cliché on the risk management lecture circuit that you need not just technical knowledge, but judgment, mainly by senior executives who don’t have any technical knowledge.  Even in these stressed times, Taleb was dead wrong on VAR, in that in spite of his criticisms it is ubiquitous as a method for amalgamating short-term risks from different instruments into a single metric.
VaR is not useful for allocating capital, or estimating the cost of equity, but it is useful in keeping your traders honest. It allows one to measure risk given various assumptions, and like any model it is garbage in-garbage out. The recent financial crisis has often been blamed on VaR. To the extent certain banks applied VAR to mortgages, using, say, a 10-day VAR based on data from the benign 1990s, was an error. Yet, the ubiquity of this error suggests it was not a mathematical mistake (math errors are random and go in both directions), rather a flawed assumption that implied benign VAR exercises: the fact that housing prices do not decline. One can say with hindsight, this was incredibly stupid, yet no one was arguing for financial institutions must be robust to this scenario prior to 2007, and the government regulators were actively encouraging no downpayment, no documentation loans as part of a multipronged effort to increase home ownership. That is, the mistaken assumption was part of a broader mistake, comprehensible to all, not some technical error by risk managers, because that assumption was not theirs to make; it was part of a zeitgeist that people seem to forget like all those who forgot voting for Nixon after he resigned. Most importantly, VAR is not perfect, nor a panacea, but the onus is on critics to describe a better alternative. Using 'judgment' or 'all one's information' seems better with hindsight, yet as foresight this is so undefinable it would be a signficant step backward.
If you were to list all the financial company bankruptcies, the one common thread would be that they blindsided investors with their exposures.  Who knew Orange County had such a position against interest rates ex ante in 1994?  Who knew Barings had such an exposure to a trader in Singapore in 1997?  These were not properly calculated risks that went awry, nor were they outright fraud where an unauthorized intraday position blew up. They were the result of investors or management not fully understanding the risks that were being taken, which often a correctly calculated VAR number, correctly communicated, would have easily shown.  The errors were problems in getting an accurate VAR, which clearly needs people getting accurate data on positions.
If operating risk is the primary reason why trading operations fail, emphasis on refining VAR seemingly misses the point. Operating risk is neglected for good reason, however, in that it is extremely difficult to quantify existing operating risks, which in turn makes it nearly impossible to evaluate methods of monitoring and reducing these risks.  Just as Eisenhower stated it is essential to plan prior to battle even though once a battle has commenced the plan is useless, VAR is essential in planning the allocation of capital, yet in risky situations becomes useless.  This is not a paradox, but merely the fact that when we train for competition, we practice tactics and strategies.  Inevitably competition, especially competitions we ‘lose’, will bring forth situations we have not prepared for, but the best preparation for such an occurrence is not nihilism, but more practice.  And indeed many new situations are avoided by practice, which is why we learn math by solving old problems, because we think these tools are useful to unknown new problems. The alternative, to instead focus on operational risk, is such an undefined objective, that it is much less salutary.
Taleb argues that the unpredictability of important events implies we should basically forget about all that is predictable, because that’s not where the real money or importance is.  So from a risk management perspective, we should ignore Value at Risk, which measures anticipated fluctuations.  Further, we should ‘go long’ on these unanticipated events by engaging in quirky activities on the off-chance that we randomly find something, or someone, really valuable. 
Success in markets, like life, is a combination of ability, effort, and chance.  Much of intelligent thought is distinguishing between what is predictable versus what is unpredictable; it is to any organism's advantage to find out what we can figure out and change, and what is forever mysterious and unalterable (eg, the Serenity Prayer).    The brain is constantly predicting, trying to figure out cause and effect so it can better understand the world.  Most of what humans process is predictable, but because we take predictable things for granted, they are uninteresting. We can't predict some things, but instead of resorting to nihilism, we merely buy insurance or manage our portfolios--in the broad sense of the term--to have an appropriate robustness.   Discovering certain things are basically unpredictable does not diminish our constant focus on trying to predict more and more things. People will disagree on which risks at the margin are predictable, but that's to be expected, and we all hope to be making the right choices that optimize our serenity at the margin of our predictable prowess.

From Taleb's Wikipedia entry circa July 2006, we see where Black Swan thinking goes when applied to an investment strategy: 
When he was primarily a trader, he developed an investment method which sought to profit from unusual and unpredictable random events, which he called "black swans." His reasoning was that traders lose much more money from a market crash than they gain from even years of steady gains, and so he did not worry if his portfolio lost money steadily, as long as that portfolio positioned him to profit greatly from an extremely large deviation (either a crash or an unexpected jump upwards).
In fact, Mandelbrot also argues for this strategy.  Taleb co-authored a paper arguing that most people systematically underestimate volatility. Furthermore, he argues there exists not only a lack of appreciation of fat tails, but a preference for positive skew, in that people prefer assets that jump up, not down, which would imply the superiority of buying out-of-the-money puts as opposed to calls because those negative tails that increase the price of puts are unappreciated.He is affiliate with some fund that tend to be long tail risk, presumably by being long deep out-of-the-money options, but selling at-the-money options, a locally delta and vega neutral strategy.

These assertions present some straightforward tests, which a Popperian like Taleb should embrace. Specifically, buying out-of-the-money options, especially puts (because of negative skew), should, on average, make money. But insurance companies, which basically are selling out-of-the-money options, tend to do as well as any industry (Warren Buffet has always favored insurance companies, especially re-insurers, as equity investments). Studies by Shumway and Coval (2001)and Bondarenko (2003) have documented that selling puts is where all the extranormal profit seems to be. Of all the option strategies, selling, not buying, out-of-the-money puts has been the best performer historically. Further, Sophie Nifinds that out-of-the-money options are more overexpensive the degree they are out-of-the-money.
Malcom Gladwell wrote a 2002 New Yorker article contrasting the thoughtful, pensive Taleb versus the brash cowboy Victor Niederhoffer: Taleb buys out-of-the-money puts, Niederhoffer sells them.  Taleb is betting on the big blow up, Niederhoffer on the idea that people overpay for insurance.  Who was right?  Well, Niederhoffer ran his flagship fund until September 2007 from a  chalet-style mansion in Weston Connecticut .  Taleb shut down his Empirica Kurtosis fund at the end of 2004, and the only public data on it suggest a rather anemic Sharpe ratio (up 60% in 2000, but then fluttered). Later Taleb described the fund as a hedge or laboratory. While neither strategy was great, and returns are proprietary, I venture that Niederhoffer's was better if you would just look at their lifetime Sharpes. Taleb's latest funds, which he is less involved with day-to-day but implement his basic beliefs in extremes, were up significantly in 2008, though this is to be expected given the extreme decline, and is similar to how Empirica started. 
Taleb's big problem is that he misinterprets the mode-mean trade. A mode-mean trade is where a trader finds a strategy with a positive mode, but zero or negative mean.  He then uses someone else’s capital to make money off several years of good returns, making good money for creating or managing the strategy, then, when the strategy gives it all back, the investor bears all the loss.  The zero mean means that all the modal returns come crashing down in short time, generating large losses, and the manager walks away with his il-gotten bonuses from the benign modal periods. That’s a bad strategy for the investor, and the trader who manages it is either naïve or duplicitous.   High Yield debt is a good example, as the stated yields are quite high, but the total returns to B rated bonds is the same as for BBB rated bonds, at several times the risk (and very concentrated in recessions).  However, just because selling puts is a bad strategy, it doesn't mean buying puts is a good strategy. A Sharpe of 0.2 is a bad long position, but a worse short.
A ‘Black Swan’ is something that is totally unexpected and important. [European] people assumed all swans were white, but then they saw a black swan, and everyone certain all swans were white was wrong!  That’s a 'gotcha game' for people who really take seriously someone’s assertions on the color of birds.   But when there’s a price involved, the payoff to such an insight is not obvious, if not totally absent.  For example, London bookmakers offer ‘only’ 250-1 odds a perpetual motion machine will not be discovered, and 100-1 odds aliens won’t be contacted: longshots ignored in a casual context are usually overpriced in actual markets. 
In option markets, there is a volatility smile, whereby out-of-the-money options have higher implied volatilities, especially on the downside. For example, in May 2006 when rumors of GM's woes were large and its stock price was around 32, GM options had a one-year at-the-money implied volatility of 60, but down at a strike price of 15 its volatility is a much higher 140. The fact that Black-Scholes assumes lognormal returns does not imply market participants think likewise, so it is simply incorrect to assert that a market collapse of 23 standard deviations has a infintesimal probability based on the normal distribution, because real markets are aware of fat tails. Perhaps options were priced this way in the 1980's, but since then, there is a volatility smile that directly captures non-nomality. You can't profit from the idea that market returns have fat tails because that's priced into the market via the volatility smile, and this volatility smile shows up in 'disaster' insurance of all types: People pay a lot to sleep easy. Many people have looked at option prices, and they all find that out-of-the-money puts are the most overpriced of all options—people are expecting ‘Black Swans’ too much on average.

Taleb responds by noting that the 1987 stock market crash changes everything, because if you bought puts then, you would have made enough money to make up for decades of otherwise weak performance. While Shumway and Coval do not include 1987 in their academic study, Bonderanko does, and gets the same results. Taleb points out several anecdotes of financial market crises as further evidence of the importance of financial debacles, such as the 1998 crisis related to Long Term Capital Management (implied vols, libor spreads, skyrocked), or the emerging markets blow up of 1997.  These events made money for people with long volatility, or specifically long puts, but the plural of anecdote is not data, so he should have cited an empirical paper showing the positive abnormal returns to taking on fat-tailed or asymmetric risk. Though it is easy to recall extreme events that would generate large fortunes to those on the correct side, one has to put them in full context, against the cost of insuring against these events over long periods of time.  What is the sample space of all things one is insuring against? Stasis is data, as Stephen Jay Gould used to say. The volatility smile, and large bid-ask spreads in the extremes as a function of price, imply  you can’t make extranormal profits over the long run by going long ‘Black Swans’ - at least in the markets where Taleb has the most experience (though not, according to him, expertise, which is more philosophically oriented).   
The bottom line is that people tend to underappreciate low probability events when they are immaterial--because they are immaterial!  So they underestimate the  prevalence of Black Swans because if you find one, who cares?  But hurricane insurance, a 3-delta put option on GM?  You will pay up for that. 

In the end, he promises to teach us how to take advantage of these Black Swans. His strategy is pretty simple. He argues for a barbell strategy of much safety, and a dollop of wild risks, which is, basically, an exposure to something totally unquantifiable, like Llama farms, or any of the myriad opportunities neighbors, spammers, and late-night paid-TV tout.   In the context of Tobin’s two fund separation theorem, this means the ‘efficient’ risky portfolio is the most insanely unquantifiable and risky portfolio you can imagine, tempered by its modest allocation.  Yet this implies the unquantifiable and risky portfolio has very good returns, which by definition (unquantifiable) is merely an assertion. As per the super safe assets, the only consistent risk premiums are from extending from overnight to a couple years in bond maturity, and from going from AAA to BBB credit risk. Super safe, is generally 'too safe', in that economists find this risk premium outsized relative to its volatility or covariance difference. 
There is good reason to suspect one loses money, on average, on the wildest risks.  Consider longshot odds at the racetrack and the highest payout (and thus riskiest) lottery tickets.  Researchers have found a negative return premium for highly volatile stocks.  Applied to ‘uncertainty’, this same pattern holds, as stocks with the most earnings forecast estimation error also have the most volatility, so it is no surprise they too have a negative premium. Truly improbable scenarios generally involve more hope than rational investment, as people will pay you to help them dream of the chance to become incredibly rich in the same way that the biggest lotteries, with 100 million to 1 odds, have the highest jackpots and the lowest mean returns.  There are an infinite number of companies that directly target people wishing to make an end run around the rat race, and most of these companies are engaged in selling nothing more than hope (seeImergent).  
Black Swan argues that standard statistics is flawed because it is backward looking — it uses ‘historical’ data — and argues that standard measures of risk like the normal distribution are ‘frauds’.  I too prefer future data, but it ishardly a practical alternative. The Gaussian distribution is common in theory because it is so analytically tractable; it often creates closed form solutions that allow one to see how one variable affects another, and has nice properties, such as the fact that two Gaussian random variables added together is also a Gaussion random variable.  In practice, no one actually believes in this view, and makes ad hoc adjustments, such as the volatility smile for option prices.  The key is that from an expositional point of view, the Gaussian distribution usually gives one the gist of the true ‘fatter-tailed’ distribution, and allows easy exposition.  Non-economists often giggle at the term ‘fat-tailed’ or homoskedasticity, but indeed most real world distributions are not ‘Normal’ or Gaussian, they simply have fatter tails than average.  Does this imply statistics is a fraud?  Well, if you mistake the map for the territory, indeed, this is news.  For everyone with some common sense it’s an approximation or expositional device. 
Taleb belittles predictions that have large or unmentioned error rates, yet any specific error metric (standard deviation, value-at-risk, correlation, R2, etc) is, in his mind, a fraud and useless because it relies on an assumption, one that is 'wrong'.   He argues we reward those who imagine the impossible, but what does that mean in practice? That we encourage people to enumerate everything possible no matter how improbable?  In finance, these  risk reports are all too common because they reflect a lot of work, in that generating a list of unprioritized things that could happen is easy but practically useless, because you simply can’t address all the points and so must leave them as mere ‘I told you so’ observations.  One can remember Richard Clarke’s vague warning about Al Qaeda prior to 9/11, which in no way suggested that changes to hijacking protocols or airline boarding should be made, but rather that something could happen, true but unhelpful. 
Getting people to highlight wild risks comes easy, which I think is a big part of his book’s appeal.  Legislators and personal-injury lawyers eagerly hype risks with negligible real impact, like secondhand smoke, or getting cancer from trace amounts of chemicals. Sometimes they create considerable public concern about risks that don't exist, like that of contracting anti-immune disease from breast implants, or cell phones causing cancer.  Newsrooms are full of English majors who make confident pronouncements about global-warming or some other complicated process, all in hopes of getting viewers or readers activated. 
I could imagine Taleb teaching a statistics class to freshman and instead of starting with the arithmetic mean and standard deviation, asking 'what was the probability of an airplane taking down the World Trade Center on September 10, 2001?', and waxing poetic about how ‘we just don’t know!” Students might think such talk is much "cooler" than boring formulas, but such confused thinking leads nowhere in particular and can be indulged indefinitely without producing anything useful, as Taleb demonstrates.  Of course one needs technical knowledge and common sense in anything, but while you can teach one, you can't teach the other.  We teach statistics, calculus, etc., not because it solves every problem, but because it can help in many problems to delineate and potentially manage that which we can change from that which we can’t. Surely a college department of 'wisdom' or 'good judgment' would be a valuable thing, unfortunately no one can agree on the curriculum. 
Martin Gardner wrote a popular column for Scientific American, and in the process received a lot of mail from ‘cranks’ telling him about perpetual motion machines and the like. So he wrote a book called Fads and Fallacies. In the book he describes "cranks" as having five invariable characteristics:
  1. They have a profound intellectual superiority complex.
  2. They regard other researchers as idiotic, and always operate outside the peer review 
  3. They believe there is a campaign against their ideas, a campaign compared with the persecution of Galileo or Pasteur.
  4. They attack only the biggest theories and scientific figures.
  5. They coin neologisms.
On his personal website, Taleb once described himself as being "an essayist, belletrist, literary-philosophical-mathematical flâneur," a conception that some people finding endearing, me not so much.  Literary-philosophical-mathematical types,- especially flâneurs - tend to be 'full of themselves,' supporting Gardner ’s characteristic #1. He prides himself on not submitting articles to refereed journals, considers most people who are indifferent to him as fools, and disdains editors, even spellcheckers (#2). He proudly notes that someone told him “in another time he would have been hanged [for what, inanity?].” Wilmott Magazine, a quant publication published by his colleague Paul Wilmott, wrote a fawning article about him in which they noted that he is “Wall Street’s principal dissident. Heretic! Calvin to finance’s Catholic Church” (#3). His website states his modest desire to understand chance from the viewpoint of “philosophy/epistemology, philosophy/ethics, mathematics, social science/finance, and cognitive science”, supporting #4. Lastly, for #5, he has gone so far as to print a glossary for his neologisms (eg, “epistemic arrogance” for “overconfidence”). In Martin Gardner’s taxonomy, Taleb is a classic crank.

Clearly his experience as an options trader gives him credibility, but I think this is a big issue, that of successful brokers thinking they made their money off investing insights. Before he became a regular on the talking-head circuit and expert on Judeo-Arabic philosophy, he was primarily a trader for large market makers. These are not speculators investing their wealth based on insights, but more like brokers, making money off customer flow, only their buyers and sellers are the guys on the phones talking to retail clients.  Such traders spend most of their time looking at a model such as Black-Scholes that tells them what price to buy and sell based on some underlying parameters. These models are more or less standard, and so the main thing the market maker has to do is keep his model inputs fresh, post prices to potential buyers and sellers, fill market orders, and pick off stale limit orders. Customers generally have access to older prices, and in a situation where the current price moves every second, this clearly puts a trader at an informational advantage, which is why it was such a lucrative field, especially in the days before the internet became big (ie, Taleb's time). The trader makes money irrespective of movements in the underlying model price, as in general he keeps his exposure to first-order (eg, delta) and second order (eg, vega) risks as close to zero as possible.

But such trading skill is quite distinct from what a speculator or investor does, which involves a directional bet on the first or second order risks that traders normally try to erase. Traders know as much about what makes prices move as plankton knows about what makes the tides move. Much of being a trader is encouraging trading activity from a hesitant broker, and so many traders are quite adept at presenting themselves as more than middlemen, but also men with an angle or a story. A good trader is probably truly delusional about his prognostic abilities because this allows him to appear sincere in his sales pitch for the latest trade idea; those who don't believe their own stories make weak sales pitches (see Robert Trivers, who Taleb mentions favorably in The Black Swan, and note the irony endemic in his writings). Most of these traders are certain they could make money without their customer flow, because the same self-deception that serves them well chatting up brokers or impressing their boss generates delusions of strategic grandeur. Supreme self-assurance, even if undeserved, just as much as knowing your Greeks, makes for a good trader . Thus Taleb’s ‘narrative fallacy’ argument plays right into his own biases, that is, he has fooled himself into thinking he knows 'the big picture' because that delusion was helpful in his own career.

Rich investor or rich broker: Who is the more easily fooled about his alpha? Notice the relation to the theme of Fooled by Randomness? Taleb is consistently amusing because his criticisms of others apply so neatly to himself: he claims he is an empiricist yet supports his points with anecdotes. The Black Swan makes fun of ‘experts’ with credentials, but he states he does not deign to engage with anyone not sufficiently expert; he states he is not interested in being a speaker-bureau commodity , but routinely travels the rubber chicken circuit; he derides forecasters who don't give a full accounting of their prior forecasting history, yet delinks old remarks about Value-at-Risk, and recategorized his extinct Hedge Fund as a hedge, not a fund; he claims to prize humility, yet is most immodest; he argues against applying the law of large numbers, and also of inferring too much from small samples;  people apply models to reality in biased manner, people naively extrapolate data without the appropriate theory; forward thinking is adaptive, forward thinking is error-laiden.  Some people think inconsistency is a sign of genius; I think it just reflects confused thinking.
Inconsistency is the major problem with Taleb's oeuvre. For example, he often praises the work of Danny Kahneman as one of the uniquely prophetic economists, famous for his 'prospect theory' that explains why people will be risk seeking in small losses in but risk loving over large gambles. That is, Prospect Theory was invented to explain why people will pay small amounts to gamble, but are risk averse over gains. Yet Taleb argues that a predominant financial vice is the mode-mean trade, where people desire to make a little bit every day, often at the expense of blowing up on 'fat tail' events. These are opposite theories, which would not be a big deal if they were minor assertions from these men, but in fact they are the signature financial hypotheses of each. Taleb may appreciate Kahneman's diverse work, but one would expect him to be a harsh critic of this seminal idea, not the huge unqualified fan he is.
To be popular it is helpful to make people think they are learning something new about something novel and important. Yet the masses do not really like novelty, they like affirmation of their inchoate prejudices. Thus, a reader can leave The Black Swan thinking that any expert is either a charlatan or a fool except Taleb and those smart enough to appreciate him, a group that prides itself on knowing what they don't know, that any specific model is imperfect and therefore evidence is naive Platonism.  The current financial crisis may make radical theories that suggest junking existing theory more attractive, but remember that the Great Depression was a Black Swan, and this did not help macroeconomic theory so much as lead it into the desert for 40 years, giving many a wasted life championing not merely a welfare state, but socialism and all its unintended horrors. If something really unpredictable happens, the large number of perennial disparate forecasters of disaster, combined with bayesian statistics, still implies those calling for the end of times are probably 'lucky fools', as Taleb would say. I do agree his claims of an extreme event were spot on over the past year, but this is no less impressive that Henry Blodget's Amazon call in 1998, Elaine Garzarelli calling the 1987 stock market crash, orAngelo Mozilo's subprime investment success up to 2006 made him correct. I look to broader historical data and see buying out-of-the-money options is poor investment strategy, so I don't consider recent events proof of some really useful truth.
To the degree The Black Swan has argument about the essence of risk they are at least a generation old, even if many are pleasantly introduced to them for the first time (fat tails see Mandlebrot (1962), nonquantifiable risk see Knight (1921), for various cognative biases see Kahneman, Slovic and Tversky (1982) which was a compilation of papers mainly done in the 1970's), and these books have spawned, or are clearly referenced, by literally thousands of books. The Black Swan may popularize the concept of low probability events, what were called 'peso problems' (see Rietz 1988), and that would be a good thing. But ultimately, the bumper sticker "shit happens" is kind of funny, kind of true, but hardly profound.

Friday, January 28, 2011

Lindy Effect and the future

Tuesday, January 25, 2011

Taleb made 67000 percent betting on black swans


Source:
http://www.pma-corp.net/OT/OptionsTrader2006-02.pdf

betting on deep out of the money options is probably the safest way to make lots of money, and the surest way of losing a very small amount of money.

A 67,000 percent return basically means, that for every 100 dollar invested, you make 67,000 dollars. It definitely is a gargantuan proposition. Plus, the downside is that you lose 100$, with very high frequency.

The crux of the idea is to trade deep-out-of-the-money options betting on the fact that there would be extreme volatility at some point in time.

If 10 days are removed from the S&P 100 index then the net worth of the index drops by about 50%., which basically translates, that in 10 years, only 10 days were responsible for 50% of the gains in the S&P index. Now imagine what you could have made if you had exposure to those 10 days.

Nassim Taleb made 67,000 percent in the crash of 1987, simply because everyone thought that market volatility is a thing of the past.


Saturday, January 15, 2011

Human Accomplishment and the Black Swan

Charles Murray and Nassim Taleb

http://www.c-spanvideo.org/program/199808-4&showFullAbstract=1

Monday, November 8, 2010

Convex function vs Concave function

Nassim Taleb's staircase is a very good model for describing life. If life could be treated as a function then it should be a convex function which is not smooth.

Definition of a convex function:

  • A function which always gains more than it loses
The function shown in the image is an example of a concave function. Life is generally a staircase, where there is relative stability for extended periods of time followed by a jump or a fall. When modeling or making decisions in one's life, one must always insure that the fall should be lesser than the rise. People taking too much downside risk would represent the concave function shown above. The fall should always be lesser. 

Investments (time, work, capital) should be made in opportunities that have enormous upsides where as the downside must be insured. For example, when starting a business, make sure that you have something to fall back on if the promised business plan never materializes. Start your first business without taking too much risk, preferably while working and only quitting once the business generates the positive results. 


anti-fragility (Nassim Taleb)

Here's a link on Taleb's take on anti-fragility

http://www.fooledbyrandomness.com/af.pdf

Nassim Taleb's practice of Skepticism: Consequences and Relevance

Nassim Taleb explains the skepticism is a difficult practice and is generally domain dependent. We have limited reserves and are not natural skeptics. We should therefore be skeptic of consequential ideas such as nationalism, economics, bioinformatics, nuclear research. Religion once used to be consequential but no longer is, and therefore this obsession with religion should be pushed to the back burner. 


link to the original article (LINK)


THE OPIATES OF THE MIDDLE CLASSES

[NASSIM TALEB:] As a practitioner of science, I am opposed to teaching religious ideas in schools. But, it seems to me somewhat misplaced energy — more of a fight for principles than for any bottom line. As an empirical skeptic, I would like to introduce a dimension to the debates: relevance, consequence, and our ability to correct a situation — in other words the impact on our daily lives.

My portrait of the perfect fool of randomness is as follows: he does not believe in religion, providing entirely rational reasons for such disbelief. He opposes scientific method to superstition and blind faith. But alas, human skepticism appears to be quite domain-specific and relegated to the classroom. Somehow the skepticism of my fool undergoes a severe atrophy outside of these intellectual debates:
1) He believes in the stock market because he is told to do so. — automatically allocating a portion of his retirement money. And he does not realize that the manager of his mutual fund does not fare better than chance — actually a bit worse, after the (generous) fees. Nor does he realize that markets are far more random and far riskier that he is being made to believe by the high priests of the brokerage industry.
He disbelieves the bishops (on grounds of scientific method), but replaces him with the security analyst. He listens to the projections by security analysts and "experts"— not checking their past accuracy and track record. Had he checked them he would have discovered that these are no better than random — often worse.

2) He believes in the government's ability to "forecast" economic variables, oil prices, GNP growth, or inflation. Economics provide very complicated equations — but our historical track record in predicting is pitiful. It does not take long to verify these claims; simple empiricism would suffice. Yet we have confident forecasts of social security deficits by both sides (democrats and republicans) twenty and thirty years ahead! This Scandal of Prediction (which I capitalize) is far more severe than religion, simply because it determines policy making. Last time I checked no religious figure was consulted for long-term business and economic projections.

3) He believes in the "skills" of the chairmen of large corporations and pays them huge bonuses for their "performance". He forgets that theirs are the least observable contributions. This skills attribution is flimsy at best — there is no account of the possible role of luck in his success.

4) His scientific integrity makes him reject religion but he believes the economist because "economic science" has the word "science" in it.

5) He believes in the news media providing an accurate representation of the risks in the world. They don't. By what I call the narrative fallacy, the media distorts our mental map of the world by feeding us what can be made into a story that can be squeezed into our minds. For instance (preventable) cancer, not terrorism remains the greatest danger. The number of persons killed by hurricanes, while consequential, is dwarfed by that of the thousands of isolated daily victims dying in hospital beds. These are not story-worthy, implying; the absence of attention on the part of the press maps into disproportionately reduced resources allocated to their welfare. The difference between actual, actuarially defined risks and the perception of dangers is enormous — and, sadly, growing with the globalization and the media, and our increased vulnerability to visual stimuli.
Now I am not arguing that one should ignore the side effects of religion — given the accounts of past intolerance. But it was in these columns that Richard Dawkins, echoing the great Peter Medawar, recommended bright students to find something worthwhile "to be smart about". Likewise, I suggest exerting our skepticism "where it matters". Why? Because, alas, cognitively, our resource to doubt is rather limited.

We humans are naturally gullible — disbelieving requires an extraordinary expenditure of energy. It is a limited resource. I suggest ranking the skepticism by its consequences on our lives. True, the dangers of organized religion used to be there — but they have been gradually replaced with considerably ruthless and unintrospective social-science ideology.

Religion gives many people solace. On a personal note I have to admit that I feel more elevated in cathedrals than in stock markets — be it only on aesthetic grounds. If I were going to be gullible about a subject, I would rather pick one that is the least harmful to my future — and one that is rewarding to my thirst for aesthetics.

It is high time to worry about the opiates of the middle class.


Sunday, September 19, 2010

Succer vs Non Sucker....Socrates vs Fat Toni

These are two chapters from Nassim Taleb's new book.
http://www.fooledbyrandomness.com/FatTony1.pdf
http://www.fooledbyrandomness.com/FatTony2.pdf

Taleb criticizes Socrate's debate with Euthyphro on piety and replaces Euthyphro with "Fat Toni" which is Taleb's rendition of an alpha male who is averse to reading books and is more worldly and street smart than most thinkers. He is abusive, gets angry, laughs, drinks and leads a life not based on theories but on instincts.

Socrates starts to question and eventually obfuscate Euthyphro on ethics. Euthyphro was on his way to execute his father over a crime but Socrates starts asking Euthyphro to define peity and justice and ethics in general. Whenever Euthyphro tries to define, there would be some contradiction and error which Socrates would use to render his actions unjustifiable. Euthyphro finally states that he knows what he's doing but he cannot define or put his thought into words. What Euthyphro really meant was that he was following his instincts but socrates insisted that actions and ideas should be defined and justified. When debating with Fat Toni, Socrates is left speechless because Fat Toni argues that Socrates is merely confusing people about things which they know is right instinctively. The whole argument is about the value of knowledge and how seriously theories should be followed. Whether technology came first or the theories supporting the technologies came first. The whole question being debated is that humans are not naturally inclined towards knowledge and theories which in retrospect are mostly useless. On the other hand knowledge and theories have actually been derived post-hoc. Modern knowledge is about lecturing birds about flying. Birds know how to fly instinctively and mostly learn by tinkering, on the other hand ornithologist make theories on how birds learn to fly.

The two chapter are a must read, mostly for amusement and that personal pleasure over knowing that all those nerds out there are idiots.

Sunday, September 12, 2010

Taleb's take on "Happiness" and why Less is Sometimes More

Iatrogenics of wealth: (LINK)

As a child I was certain that poor people were happier because they had less complicated but more social lives, huddled together in small quarters, and having no soccer mom (or the then-equivalent), they could just play in the streets etc. In addition, rich people use harmful technologies, go to the gym instead of playing in the streets, meet economists and other frauds, etc... So there were things money could not buy, in effect, money caused you to lose... Later on when I got a windfall check, in my twenties (before it became more common for people in finance to get big bucks), I discovered another harmful side of wealth: unless one hid the cash, it was hard to know who one's friends were...

But for some people, money can be beneficial –some. I am not convinced of the utility theory approach & results showing the absence of effect of higher income (in excess of lower-middle class wages) on happiness (the noise I see in the research papers is MONSTROUS, even if the "average" seems to accord with the findings). Also, I am not quite certain that "happiness" is refined enough an expression. People don't quite understand what being human means. There is the unhappiness that's natural to mankind, sadness from heartbreak or the loss of a family member (Why do so many people read sad love stories?) and the unhappiness of working in an office building, commuting, sitting in a structured classroom, captive in a technological nightmare... more later.

Monday, September 6, 2010

Traditional Values vs Modern Nation States

This was written in reply to an article written by Danielle Ali Shah who is an Aussie expat living in Pakistan. She is a convert to Islam and writes frequently about the way of life in Pakistan. To read the article (link).


Interesting article. I am glad that you found the logic behind what makes pakistan so interesting, especially for pakistani’s living abroad.

I have been interested in comparatively studying religious\cultural mythology and modern systems and i have come to a borrowed conclusion which is similar to the article mentioned above. But i was looking into finance rather than the average day to day lives of people living in different countries.

 Financial systems in the west are overly regulated and centralized. And they are built on the concept of debt. Its all top-down thinking, a Harvard economist decides what policies suit the average person in a developed country. Top down thinking is notoriously risky although most ivy league economists would say that they are risk averse. They encourage people and businesses to take risks backed by debt. This is unraveling right now and long term viability of debt ridden western countries is risky, Greece and Dubai are a case in point.

The traditional system, which you defined as the “every man for himself” system is a lot more defensive and is
built on a bottom up thinking. The millions of small economic units (working men/women) decide what the shape of the whole economic system would be like. Traditionally all religions have endorsed that debt is bad or evil.

I think that religion or general traditional and cultural beliefs are stress tested by time. They are redundant and have evolved over thousands of years and are generally defensive in nature e.g modesty for men and women, debt, zakat etc. They are defensive against the worst case scenarios.

Modern systems on the other hand are pulled by prosperity and generally aren’t insured against worst case scenarios. The are optimized to get the best possible outcome. They also haven’t been stress tested by time and most of modern thinking has barely existed for a few hundred year. Even in these few years negative results are showing up e.g unstable demographics, climate change, unstable boom and bust economies etc.

What happened in Katrina in USA could be compared with the Kashmir earthquake of 2005 as evidence of this defensiveness against worst case scenarios. One country had an excellent system in place but failed. Another country did not have a system in place but had cultural values that were specifically tailored for such a situation. The reaction in Pakistan to the earthquake was breath taking when almost every single person in Pakistan contributed to an effort to save the survivors and the fact was not a single person was running or in charge of the rescue effort. It felt like the whole of Pakistan was traveling to Kashmir on bus, on car or on foot, traveling to save earth quake survivors all on their own.

Whats wrong with Pakistan is that it is a hybrid of both systems. The cultural day to day living is still traditional, whereas the economic system is modern (scientific) or overly regulated. The over regulation and taxation must end and government role must be reduced. We should definitely have a republican party here in Pakistan.

The Age of Outliers

I have just had a eureka moment as I was reading an article about a Quran burning ceremony taking place somewhere in a remote location in America. The author wanted to kidnap the pastor for such an outrageous event which he rightly points out would anger Muslims across the world and may lead to more revenge attacks against Americans. In response to the article, someone stated that it was a complete non-event as no one probably was going to attend the ceremony in that remote corner. His advice was that main stream media should stop giving coverage to such people as they represent no one. The same argument could be made when the cartoon controversy emerged. An unknown newspaper published a few cartoons and that triggered a chain reaction which was felt across continents. The same was the case with the "Draw Muhammad" day. Nine eleven could be thought of as a super set of such outliers where 19 unknown youngsters hijacked planes and rammed those planes into buildings.

My hypothesis is that as the world is shrinking and becoming a global village, then these outliers and their intensity is increasing. The world has gone through major upheavals instantly because of the wired nature and connectivity of this global village. A few decades ago the world was not connected hence every incident was localized. No one in Pakistan would hear about Quran burning ceremonies in some remote American town or vice versa, no one in some remote American town even knew what the Quran was. The internet/media/etc were meant to educate people but have actually spread rumors and misinformed opinions like wild fire.

Previously, people in the west were educated by Muslims about Islam. With the human element missing, Islam looks and feels a lot worse. In addition gross uninformed articles and rubbish is spewed out on the internet to defile and defame others, both collectively and individually. The same goes against the west as well, as many Islamic extremists are able to spread their distorted messages with ease and are able to target a much wider audience. 0.0001% of the people of this planet are now capable of influencing and changing the coarse of history. 

These upheavals in world history will be more frequent with the current connectivity and we must welcome ourselves into this New Age of Outliers.

Wednesday, September 1, 2010

Life's Barbell: Fasting for Health

Human's have lived natural lives for millions of years. That lifestyle consisted of hunting and gathering food, being hunted for food by other animals, surviving through lack of water and drought etc. We were used to a way of life which was completely random with many highly stressful events. Imagine yourself surviving on little food when faced with a drought, leaving few animals for hunting. On the other hand there would be times when food would be plenty, each hunting party bringing in many kills every night. We would lose and gain weight, dictated by the capricious weather system. Humans from different regions would adapt to their environment. Orientals are small in size simply because they live in the tropics and need to climb trees for survival. People living in the tropics would have diets that would contain more fruits and nuts because of their abundance. On the other hand people living in plain areas would probably be more dependent on hunting. The point still is that our diets were much more random and erratic than the regular three meals that we get today. Another point is that, since our diets were erratic hence a survival mechanism must have evolved which would be able to take advantage (or at best survive) this erratic nature of our ancestral dietary habits. If that is the case then, we probably are not used to the high calorie three meals that we get daily.


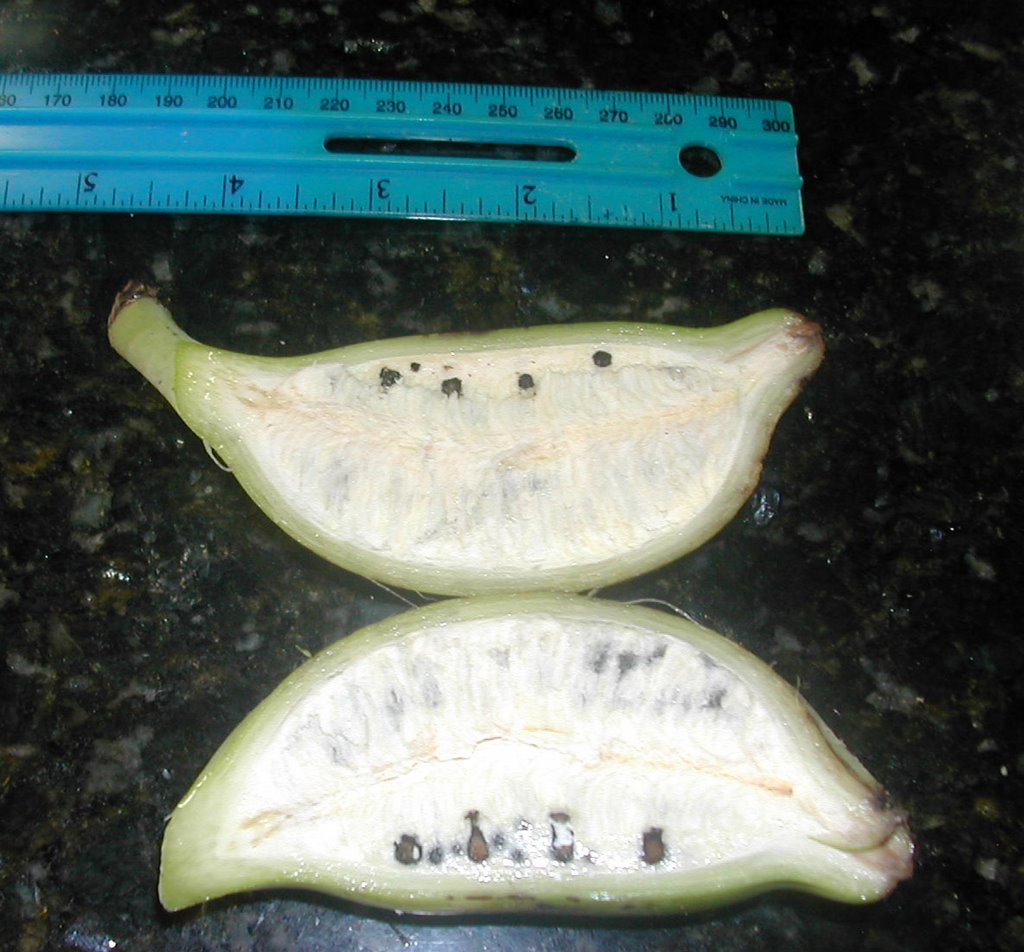
The high sugar content in our meal has forced our pancreas to work over time. Most people become diabetic early in life and this has now become a very common disease. The increase in sugar content can be attributed to the agrarian lifestyle we adapted a few thousand years ago. Carbohydrates themselves are therefore unnatural, especially in the form of wheat and rice. Its hard to imagine ancient humans having anything to do with rice and wheat. These were wild plants that were discovered much latter and most of the carbohydrates derived came from wild vegetables and fruits.  These fruits also did not look anything like the genetically modified fruits seen in our local super markets. These fruits were much smaller and less sugary then their modern counter parts. I have posted a picture of a wild banana to give you an idea about what we were used to eating.
Now coming back to the topic, fasting has been a very ancient ritual found in many traditions and religions. No one really knows what the origins are. In my opinion fasting probably came from rituals which were derived during periods of drought. As humans migrated during dry seasons then their food supplies would run low. Rituals like fasting were probably helpful in reducing the food intake of the tribe on the move and must have helped during tough times. The mythological aspect of fasting can be easily derived from one spiritual leader (prophet) in the tribe who probably built an entire mythology around the idea. An interesting thing about mythology and their development is that only those mythologies survive that actually use the same prevalent ideas. Mythologies that are radically different from the social norms are generally rejected. If one studies Islam, then it is extremely difficult to differentiate the original creed from Judaism which was thought superior to the Arab creeds at the time. Almost all ritual, social and moral ethics of Islam are copy pasted from Judaism, except that it is worded differently. The point is that fasting probably preceded the mythology.

Lets examine how fasting helps physically and mentally. The most cited scholar on the subject is Mark P. Mattson who has conducted several studies on mice and studied the physiological aspects of altering caloric intake. Mark has discovered that many age related and cardiovascular diseases can be tackled by intermittent fasting and binging. This could also be achieved by simulating the much more unpleasant semi starvation diet but intermittent fasting with excessive binging is much more pleasant. Feasting and famine is the way to go according to Mark if one yearns to be physically fit and healthy. Chronic stress is bad but a severe shock lasting for a shorter interval is beneficial and turns on the bodies defense mechanism. The results obtained by Mark Mattson have shown the benefits of shocking your digestive system, and improvement have been seen in diabetes and Alzheimer. Its also found extremely beneficial for cardiovascular diseases and leads to better and more efficient (blood) circulatory system. Some research has also shown the effects of fasting on making cells more resistant to chemo therapy (link). Here's a link to read some of Mark Mattsson's research.

Personally I have been on a fast for twenty days with the occasional binging at night when the fast is broken. It amazes me when i realize that just twenty days ago I would have suffered immensely from hunger pangs at 12 noon but now my body has so expertly adapted to this (artificial) famine that it hardly asks for food. I can perfectly go hungry from 4 in the morning till 12 at night except that it is not recommended. If i do that, then i would be in chronic stress and its very important that i binge after 7 in the evening to break the fast.  I am currently on a complete fast which includes both food and water and it lasts for 14 hours every day. I need to also stress that a complete fast is different from living on fruit juices which are sufficiently packed with calories. To keep an effective fast one needs to make sure that one's body is capable of ketosis. Otherwise fasting could be dangerous, but most normal humans generally achieve ketosis where the body starts scraping calories from the stored fat and muscle and switches off the digestive track as nothing could be found there. In my case, after the first few days, my body adjusted and switched off my digestive track which put an end to all those initial hunger pangs. I can safely state that i am living on my back up system and the effects on my life style have been minimal. Energy levels do go down significantly as you prolong the fast but I have also experienced better concentration poweres as one's energy levels go down, which is similar to going into a meditative state. Prophets through out the world, from Budha to Muhammad have taken to fasting to improve their mental prowess and intuition.

Friday, August 27, 2010

"The Athiestic Delusion" by John N. Gray

The following article appeared in the Guardian. It is written by John N. Gray who is a British political philosopher and author of the book "Straw Dogs" in which he attacks post modernist humanism and claims that morality and ethics are mere illusions. Humans are a ravenous specie whose soul aim is to wipe out other species and as result degrade the environment in which they themselves live in. In this article he makes an interesting defense for religion which he believes is strongly under attack by fanatic secular thinkers. The reason he gives is that secular philosophies and thinkers are far more violent than the religions they attack as being violent and argues that secular ideologies are also faith based belief systems which are not dependent on rational thought as is claimed by many. The roots of these secular ideologues is in religion itself.

An atmosphere of moral panic surrounds religion. Viewed not so long ago as a relic of superstition whose role in society was steadily declining, it is now demonised as the cause of many of the world's worst evils. As a result, there has been a sudden explosion in the literature of proselytising atheism. A few years ago, it was difficult to persuade commercial publishers even to think of bringing out books on religion. Today, tracts against religion can be enormous money-spinners, with Richard Dawkins's The God Delusion and Christopher Hitchens's God Is Not Great selling in the hundreds of thousands. For the first time in generations, scientists and philosophers, high-profile novelists and journalists are debating whether religion has a future. The intellectual traffic is not all one-way. There have been counterblasts for believers, such as The Dawkins Delusion? by the British theologian Alister McGrath and The Secular Age by the Canadian Catholic philosopher Charles Taylor. On the whole, however, the anti-God squad has dominated the sales charts, and it is worth asking why.

The abrupt shift in the perception of religion is only partly explained by terrorism. The 9/11 hijackers saw themselves as martyrs in a religious tradition, and western opinion has accepted their self-image. And there are some who view the rise of Islamic fundamentalism as a danger comparable with the worst that were faced by liberal societies in the 20th century.

For Dawkins and Hitchens, Daniel Dennett and Martin Amis, Michel Onfray, Philip Pullman and others, religion in general is a poison that has fuelled violence and oppression throughout history, right up to the present day. The urgency with which they produce their anti-religious polemics suggests that a change has occurred as significant as the rise of terrorism: the tide of secularisation has turned. These writers come from a generation schooled to think of religion as a throwback to an earlier stage of human development, which is bound to dwindle away as knowledge continues to increase. In the 19th century, when the scientific and industrial revolutions were changing society very quickly, this may not have been an unreasonable assumption. Dawkins, Hitchens and the rest may still believe that, over the long run, the advance of science will drive religion to the margins of human life, but this is now an article of faith rather than a theory based on evidence.
It is true that religion has declined sharply in a number of countries (Ireland is a recent example) and has not shaped everyday life for most people in Britain for many years. Much of Europe is clearly post-Christian. However, there is nothing that suggests the move away from religion is irreversible, or that it is potentially universal. The US is no more secular today than it was 150 years ago, when De Tocqueville was amazed and baffled by its all-pervading religiosity. The secular era was in any case partly illusory. The mass political movements of the 20th century were vehicles for myths inherited from religion, and it is no accident that religion is reviving now that these movements have collapsed. The current hostility to religion is a reaction against this turnabout. Secularisation is in retreat, and the result is the appearance of an evangelical type of atheism not seen since Victorian times.

As in the past, this is a type of atheism that mirrors the faith it rejects. Philip Pullman's Northern Lights - a subtly allusive, multilayered allegory, recently adapted into a Hollywood blockbuster, The Golden Compass - is a good example. Pullman's parable concerns far more than the dangers of authoritarianism. The issues it raises are essentially religious, and it is deeply indebted to the faith it attacks. Pullman has stated that his atheism was formed in the Anglican tradition, and there are many echoes of Milton and Blake in his work. His largest debt to this tradition is the notion of free will. The central thread of the story is the assertion of free will against faith. The young heroine Lyra Belacqua sets out to thwart the Magisterium - Pullman's metaphor for Christianity - because it aims to deprive humans of their ability to choose their own course in life, which she believes would destroy what is most human in them. But the idea of free will that informs liberal notions of personal autonomy is biblical in origin (think of the Genesis story). The belief that exercising free will is part of being human is a legacy of faith, and like most varieties of atheism today, Pullman's is a derivative of Christianity.

Zealous atheism renews some of the worst features of Christianity and Islam. Just as much as these religions, it is a project of universal conversion. Evangelical atheists never doubt that human life can be transformed if everyone accepts their view of things, and they are certain that one way of living - their own, suitably embellished - is right for everybody. To be sure, atheism need not be a missionary creed of this kind. It is entirely reasonable to have no religious beliefs, and yet be friendly to religion. It is a funny sort of humanism that condemns an impulse that is peculiarly human. Yet that is what evangelical atheists do when they demonise religion.

A curious feature of this kind of atheism is that some of its most fervent missionaries are philosophers. Daniel Dennett's Breaking the Spell: Religion as a Natural Phenomenon claims to sketch a general theory of religion. In fact, it is mostly a polemic against American Christianity. This parochial focus is reflected in Dennett's view of religion, which for him means the belief that some kind of supernatural agency (whose approval believers seek) is needed to explain the way things are in the world. For Dennett, religions are efforts at doing something science does better - they are rudimentary or abortive theories, or else nonsense. "The proposition that God exists," he writes severely, "is not even a theory." But religions do not consist of propositions struggling to become theories. The incomprehensibility of the divine is at the heart of Eastern Christianity, while in Orthodox Judaism practice tends to have priority over doctrine. Buddhism has always recognised that in spiritual matters truth is ineffable, as do Sufi traditions in Islam. Hinduism has never defined itself by anything as simplistic as a creed. It is only some western Christian traditions, under the influence of Greek philosophy, which have tried to turn religion into an explanatory theory.
The notion that religion is a primitive version of science was popularised in the late 19th century in JG Frazer's survey of the myths of primitive peoples, The Golden Bough: A Study in Magic and Religion. For Frazer, religion and magical thinking were closely linked. Rooted in fear and ignorance, they were vestiges of human infancy that would disappear with the advance of knowledge. Dennett's atheism is not much more than a revamped version of Frazer's positivism. The positivists believed that with the development of transport and communication - in their day, canals and the telegraph - irrational thinking would wither way, along with the religions of the past. Despite the history of the past century, Dennett believes much the same. In an interview that appears on the website of the Edge Foundation (edge.org) under the title "The Evaporation of the Powerful Mystique of Religion", he predicts that "in about 25 years almost all religions will have evolved into very different phenomena, so much so that in most quarters religion will no longer command the awe that it does today". He is confident that this will come about, he tells us, mainly because of "the worldwide spread of information technology (not just the internet, but cell phones and portable radios and television)". The philosopher has evidently not reflected on the ubiquity of mobile phones among the Taliban, or the emergence of a virtual al-Qaida on the web.

The growth of knowledge is a fact only postmodern relativists deny. Science is the best tool we have for forming reliable beliefs about the world, but it does not differ from religion by revealing a bare truth that religions veil in dreams. Both science and religion are systems of symbols that serve human needs - in the case of science, for prediction and control. Religions have served many purposes, but at bottom they answer to a need for meaning that is met by myth rather than explanation. A great deal of modern thought consists of secular myths - hollowed-out religious narratives translated into pseudo-science. Dennett's notion that new communications technologies will fundamentally alter the way human beings think is just such a myth.
In The God Delusion, Dawkins attempts to explain the appeal of religion in terms of the theory of memes, vaguely defined conceptual units that compete with one another in a parody of natural selection. He recognises that, because humans have a universal tendency to religious belief, it must have had some evolutionary advantage, but today, he argues, it is perpetuated mainly through bad education. From a Darwinian standpoint, the crucial role Dawkins gives to education is puzzling. Human biology has not changed greatly over recorded history, and if religion is hardwired in the species, it is difficult to see how a different kind of education could alter this. Yet Dawkins seems convinced that if it were not inculcated in schools and families, religion would die out. This is a view that has more in common with a certain type of fundamentalist theology than with Darwinian theory, and I cannot help being reminded of the evangelical Christian who assured me that children reared in a chaste environment would grow up without illicit sexual impulses.
Dawkins's "memetic theory of religion" is a classic example of the nonsense that is spawned when Darwinian thinking is applied outside its proper sphere. Along with Dennett, who also holds to a version of the theory, Dawkins maintains that religious ideas survive because they would be able to survive in any "meme pool", or else because they are part of a "memeplex" that includes similar memes, such as the idea that, if you die as a martyr, you will enjoy 72 virgins. Unfortunately, the theory of memes is science only in the sense that Intelligent Design is science. Strictly speaking, it is not even a theory. Talk of memes is just the latest in a succession of ill-judged Darwinian metaphors.

Dawkins compares religion to a virus: religious ideas are memes that infect vulnerable minds, especially those of children. Biological metaphors may have their uses - the minds of evangelical atheists seem particularly prone to infection by religious memes, for example. At the same time, analogies of this kind are fraught with peril. Dawkins makes much of the oppression perpetrated by religion, which is real enough. He gives less attention to the fact that some of the worst atrocities of modern times were committed by regimes that claimed scientific sanction for their crimes. Nazi "scientific racism" and Soviet "dialectical materialism" reduced the unfathomable complexity of human lives to the deadly simplicity of a scientific formula. In each case, the science was bogus, but it was accepted as genuine at the time, and not only in the regimes in question. Science is as liable to be used for inhumane purposes as any other human institution. Indeed, given the enormous authority science enjoys, the risk of it being used in this way is greater.

Contemporary opponents of religion display a marked lack of interest in the historical record of atheist regimes. In The End of Faith: Religion, Terror and the Future of Reason, the American writer Sam Harris argues that religion has been the chief source of violence and oppression in history. He recognises that secular despots such as Stalin and Mao inflicted terror on a grand scale, but maintains the oppression they practised had nothing to do with their ideology of "scientific atheism" - what was wrong with their regimes was that they were tyrannies. But might there not be a connection between the attempt to eradicate religion and the loss of freedom? It is unlikely that Mao, who launched his assault on the people and culture of Tibet with the slogan "Religion is poison", would have agreed that his atheist world-view had no bearing on his policies. It is true he was worshipped as a semi-divine figure - as Stalin was in the Soviet Union. But in developing these cults, communist Russia and China were not backsliding from atheism. They were demonstrating what happens when atheism becomes a political project. The invariable result is an ersatz religion that can only be maintained by tyrannical means.

Something like this occurred in Nazi Germany. Dawkins dismisses any suggestion that the crimes of the Nazis could be linked with atheism. "What matters," he declares in The God Delusion, "is not whether Hitler and Stalin were atheists, but whether atheism systematically influences people to do bad things. There is not the smallest evidence that it does." This is simple-minded reasoning. Always a tremendous booster of science, Hitler was much impressed by vulgarised Darwinism and by theories of eugenics that had developed from Enlightenment philosophies of materialism. He used Christian antisemitic demonology in his persecution of Jews, and the churches collaborated with him to a horrifying degree. But it was the Nazi belief in race as a scientific category that opened the way to a crime without parallel in history. Hitler's world-view was that of many semi-literate people in interwar Europe, a hotchpotch of counterfeit science and animus towards religion. There can be no reasonable doubt that this was a type of atheism, or that it helped make Nazi crimes possible.

Nowadays most atheists are avowed liberals. What they want - so they will tell you - is not an atheist regime, but a secular state in which religion has no role. They clearly believe that, in a state of this kind, religion will tend to decline. But America's secular constitution has not ensured a secular politics. Christian fundamentalism is more powerful in the US than in any other country, while it has very little influence in Britain, which has an established church. Contemporary critics of religion go much further than demanding disestablishment. It is clear that he wants to eliminate all traces of religion from public institutions. Awkwardly, many of the concepts he deploys - including the idea of religion itself - have been shaped by monotheism. Lying behind secular fundamentalism is a conception of history that derives from religion.

AC Grayling provides an example of the persistence of religious categories in secular thinking in his Towards the Light: The Story of the Struggles for Liberty and Rights That Made the Modern West. As the title indicates, Grayling's book is a type of sermon. Its aim is to reaffirm what he calls "a Whig view of the history of the modern west", the core of which is that "the west displays progress". The Whigs were pious Christians, who believed divine providence arranged history to culminate in English institutions, and Grayling too believes history is "moving in the right direction". No doubt there have been setbacks - he mentions nazism and communism in passing, devoting a few sentences to them. But these disasters were peripheral. They do not reflect on the central tradition of the modern west, which has always been devoted to liberty, and which - Grayling asserts - is inherently antagonistic to religion. "The history of liberty," he writes, "is another chapter - and perhaps the most important of all - in the great quarrel between religion and secularism." The possibility that radical versions of secular thinking may have contributed to the development of nazism and communism is not mentioned. More even than the 18th-century Whigs, who were shaken by French Terror, Grayling has no doubt as to the direction of history.

But the belief that history is a directional process is as faith-based as anything in the Christian catechism. Secular thinkers such as Grayling reject the idea of providence, but they continue to think humankind is moving towards a universal goal - a civilisation based on science that will eventually encompass the entire species. In pre-Christian Europe, human life was understood as a series of cycles; history was seen as tragic or comic rather than redemptive. With the arrival of Christianity, it came to be believed that history had a predetermined goal, which was human salvation. Though they suppress their religious content, secular humanists continue to cling to similar beliefs. One does not want to deny anyone the consolations of a faith, but it is obvious that the idea of progress in history is a myth created by the need for meaning.
The problem with the secular narrative is not that it assumes progress is inevitable (in many versions, it does not). It is the belief that the sort of advance that has been achieved in science can be reproduced in ethics and politics. In fact, while scientific knowledge increases cumulatively, nothing of the kind happens in society. Slavery was abolished in much of the world during the 19th century, but it returned on a vast scale in nazism and communism, and still exists today. Torture was prohibited in international conventions after the second world war, only to be adopted as an instrument of policy by the world's pre-eminent liberal regime at the beginning of the 21st century. Wealth has increased, but it has been repeatedly destroyed in wars and revolutions. People live longer and kill one another in larger numbers. Knowledge grows, but human beings remain much the same.

Belief in progress is a relic of the Christian view of history as a universal narrative, and an intellectually rigorous atheism would start by questioning it. This is what Nietzsche did when he developed his critique of Christianity in the late 19th century, but almost none of today's secular missionaries have followed his example. One need not be a great fan of Nietzsche to wonder why this is so. The reason, no doubt, is that he did not assume any connection between atheism and liberal values - on the contrary, he viewed liberal values as an offspring of Christianity and condemned them partly for that reason. In contrast, evangelical atheists have positioned themselves as defenders of liberal freedoms - rarely inquiring where these freedoms have come from, and never allowing that religion may have had a part in creating them.

Among contemporary anti-religious polemicists, only the French writer Michel Onfray has taken Nietzsche as his point of departure. In some ways, Onfray's In Defence of Atheism is superior to anything English-speaking writers have published on the subject. Refreshingly, Onfray recognises that evangelical atheism is an unwitting imitation of traditional religion: "Many militants of the secular cause look astonishingly like clergy. Worse: like caricatures of clergy." More clearly than his Anglo-Saxon counterparts, Onfray understands the formative influence of religion on secular thinking. Yet he seems not to notice that the liberal values he takes for granted were partly shaped by Christianity and Judaism. The key liberal theorists of toleration are John Locke, who defended religious freedom in explicitly Christian terms, and Benedict Spinoza, a Jewish rationalist who was also a mystic. Yet Onfray has nothing but contempt for the traditions from which these thinkers emerged - particularly Jewish monotheism: "We do not possess an official certificate of birth for worship of one God," he writes. "But the family line is clear: the Jews invented it to endure the coherence, cohesion and existence of their small, threatened people." Here Onfray passes over an important distinction. It may be true that Jews first developed monotheism, but Judaism has never been a missionary faith. In seeking universal conversion, evangelical atheism belongs with Christianity and Islam.

In today's anxiety about religion, it has been forgotten that most of the faith-based violence of the past century was secular in nature. To some extent, this is also true of the current wave of terrorism. Islamism is a patchwork of movements, not all violently jihadist and some strongly opposed to al-Qaida, most of them partly fundamentalist and aiming to recover the lost purity of Islamic traditions, while at the same time taking some of their guiding ideas from radical secular ideology. There is a deal of fashionable talk of Islamo-fascism, and Islamist parties have some features in common with interwar fascist movements, including antisemitism. But Islamists owe as much, if not more, to the far left, and it would be more accurate to describe many of them as Islamo-Leninists. Islamist techniques of terror also have a pedigree in secular revolutionary movements. The executions of hostages in Iraq are copied in exact theatrical detail from European "revolutionary tribunals" in the 1970s, such as that staged by the Red Brigades when they murdered the former Italian prime minister Aldo Moro in 1978.

The influence of secular revolutionary movements on terrorism extends well beyond Islamists. In God Is Not Great, Christopher Hitchens notes that, long before Hizbullah and al-Qaida, the Tamil Tigers of Sri Lanka pioneered what he rightly calls "the disgusting tactic of suicide murder". He omits to mention that the Tigers are Marxist-Leninists who, while recruiting mainly from the island's Hindu population, reject religion in all its varieties. Tiger suicide bombers do not go to certain death in the belief that they will be rewarded in any postmortem paradise. Nor did the suicide bombers who drove American and French forces out of Lebanon in the 80s, most of whom belonged to organisations of the left such as the Lebanese communist party. These secular terrorists believed they were expediting a historical process from which will come a world better than any that has ever existed. It is a view of things more remote from human realities, and more reliably lethal in its consequences, than most religious myths.

It is not necessary to believe in any narrative of progress to think liberal societies are worth resolutely defending. No one can doubt that they are superior to the tyranny imposed by the Taliban on Afghanistan, for example. The issue is one of proportion. Ridden with conflicts and lacking the industrial base of communism and nazism, Islamism is nowhere near a danger of the magnitude of those that were faced down in the 20th century. A greater menace is posed by North Korea, which far surpasses any Islamist regime in its record of repression and clearly does possess some kind of nuclear capability. Evangelical atheists rarely mention it. Hitchens is an exception, but when he describes his visit to the country, it is only to conclude that the regime embodies "a debased yet refined form of Confucianism and ancestor worship". As in Russia and China, the noble humanist philosophy of Marxist-Leninism is innocent of any responsibility.

Writing of the Trotskyite-Luxemburgist sect to which he once belonged, Hitchens confesses sadly: "There are days when I miss my old convictions as if they were an amputated limb." He need not worry. His record on Iraq shows he has not lost the will to believe. The effect of the American-led invasion has been to deliver most of the country outside the Kurdish zone into the hands of an Islamist elective theocracy, in which women, gays and religious minorities are more oppressed than at any time in Iraq's history. The idea that Iraq could become a secular democracy - which Hitchens ardently promoted - was possible only as an act of faith.

In The Second Plane, Martin Amis writes: "Opposition to religion already occupies the high ground, intellectually and morally." Amis is sure religion is a bad thing, and that it has no future in the west. In the author of Koba the Dread: Laughter and the Twenty Million - a forensic examination of self-delusion in the pro-Soviet western intelligentsia - such confidence is surprising. The intellectuals whose folly Amis dissects turned to communism in some sense as a surrogate for religion, and ended up making excuses for Stalin. Are there really no comparable follies today? Some neocons - such as Tony Blair, who will soon be teaching religion and politics at Yale - combine their belligerent progressivism with religious belief, though of a kind Augustine and Pascal might find hard to recognise. Most are secular utopians, who justify pre-emptive war and excuse torture as leading to a radiant future in which democracy will be adopted universally. Even on the high ground of the west, messianic politics has not lost its dangerous appeal.

Religion has not gone away. Repressing it is like repressing sex, a self-defeating enterprise. In the 20th century, when it commanded powerful states and mass movements, it helped engender totalitarianism. Today, the result is a climate of hysteria. Not everything in religion is precious or deserving of reverence. There is an inheritance of anthropocentrism, the ugly fantasy that the Earth exists to serve humans, which most secular humanists share. There is the claim of religious authorities, also made by atheist regimes, to decide how people can express their sexuality, control their fertility and end their lives, which should be rejected categorically. Nobody should be allowed to curtail freedom in these ways, and no religion has the right to break the peace.

The attempt to eradicate religion, however, only leads to it reappearing in grotesque and degraded forms. A credulous belief in world revolution, universal democracy or the occult powers of mobile phones is more offensive to reason than the mysteries of religion, and less likely to survive in years to come. Victorian poet Matthew Arnold wrote of believers being left bereft as the tide of faith ebbs away. Today secular faith is ebbing, and it is the apostles of unbelief who are left stranded on the beach.


John Gray's Black Mass: Apocalyptic Religion and the Death of Utopia will be out in paperback in April (Penguin)